The Micron earnings date is Wednesday, September 30, 2026, and the popular read of it is wrong: the $50 billion revenue guide is not the aggressive target it looks like. Micron’s fiscal fourth quarter runs 14 weeks against 13 in the third quarter, a detail in the company’s own Q3 10-Q. Strip out that extra week and the guide implies weekly revenue growth of roughly 12%, below the 13% to 18% rise TrendForce forecast for conventional DRAM contract prices this quarter. Micron has beaten the midpoint of its own revenue guide by 9%, 28% and 24% in the last three quarters. Wall Street’s consensus of about $31.14 per share sits just 0.5% above the company’s $31.00 guide. A Polymarket contract prices a 94% chance of non-GAAP EPS above $32.22, which is above the top of Micron’s own range. The real question for September 30 is not whether Micron beats, but by how much, and what the fiscal Q1 2027 guide says about pricing once long-term contracts take hold.
Having tracked every Micron print through this memory cycle, I think the extra week is the single most overlooked number heading into the report. It explains why sell-side consensus looks timid, why the prediction market looks confident, and why a “beat” of 3% could still disappoint a stock that has already rallied roughly 224% this year, per TipRanks. The risk on September 30 is a smaller beat, not a miss. Last quarter Micron’s DRAM revenue grew 67% sequentially on a “low-60% range” increase in average selling prices and only a “low-single-digit” rise in bit shipments, according to the 10-Q. That is a price-driven business. When contract price growth decelerates from the 60s to the teens, the size of the beat has to shrink unless volumes or HBM mix make up the gap.
Key Facts: Micron fiscal Q4 2026 earnings
- Earnings date: Wednesday, September 30, 2026, conference call at 2:30 p.m. Mountain Time (after the US close) – Micron IR, Aug 26, 2026
- Micron’s guide: revenue $50.0 billion ± $1.0 billion, gross margin about 86%, non-GAAP EPS $31.00 ± $1.00 – Micron Q3 FY26 release, Jun 24, 2026
- Fiscal Q4 contains 14 weeks versus 13 in Q3; fiscal 2026 is a 53-week year – Micron 10-Q, Jun 25, 2026
- Consensus: EPS $31.14 and revenue $50.42 billion, versus $3.03 and $11.32 billion a year earlier – TipRanks, Sep 2026
- Polymarket prices a 94% chance that non-GAAP EPS beats $32.22 – Polymarket, Sep 21, 2026
- TrendForce forecast conventional DRAM contract prices up 13-18% QoQ in 3Q26 and NAND up 10-15% – TrendForce, Jul 3, 2026
- Micron closed at $1,015.80 on September 18 and traded at $1,039.36 in pre-market on September 21; 52-week range $154.65-$1,255.00 – Nasdaq, Sep 21, 2026
What’s Actually Happening: A $50 Billion Guide Built on 14 Weeks
Micron’s fiscal year is the 52- or 53-week period ending on the Thursday closest to August 31. The 10-Q is explicit: “Fiscal 2026 contains 53 weeks and fiscal 2025 contains 52 weeks. The third quarter of 2026 contains 13 weeks and the fourth quarter of 2026 contains 14 weeks.” Most earnings previews compare the $50 billion guide with the $41.46 billion Micron booked in fiscal Q3 and call it 21% sequential growth. On a like-for-like basis, the numbers look different.
Divide each quarter by its weeks. Fiscal Q3 generated about $3.19 billion per week ($41.456 billion over 13 weeks). The Q4 guide midpoint works out to about $3.57 billion per week ($50.0 billion over 14 weeks). That is a 12.0% rise in weekly run-rate. Even the top of the range, $51.0 billion, implies only 14.2%. The bottom, $49.0 billion, implies 9.8%. Put another way, a 13-week version of the $50 billion guide would be roughly $46.4 billion.
Think of it like a retailer reporting a holiday quarter that happens to contain an extra Saturday. The headline growth rate looks heroic, but the store’s daily takings are rising more slowly than the headline suggests. For Micron, the daily takings are what matter, because they show whether pricing is still compounding.
Compare that 12% with the market data. In early July, TrendForce said weaker consumer demand and a high comparison base would “moderate contract price increases to 13–18% QoQ” for conventional DRAM in 3Q26, with NAND contract prices rising 10–15%. Micron’s fiscal Q4 (roughly the end of May to early September) overlaps almost exactly with calendar Q3. If Micron merely matched TrendForce’s DRAM price forecast on flat bits, weekly revenue would rise faster than the guide implies. Our earlier Micron (MU) stock prediction: $1,500 bull vs $560 bear set out the valuation range; this piece is about the print itself.
The track record supports that reading. Taking the midpoints Micron published in each release:
- Fiscal Q1 2026: guided $12.50 billion and $3.75 non-GAAP EPS; delivered $13.64 billion (+9.1%) and $4.78 (+27.5%)
- Fiscal Q2 2026: guided $18.70 billion and $8.42; delivered $23.86 billion (+27.6%) and $12.20 (+44.9%)
- Fiscal Q3 2026: guided $33.5 billion and $19.15; delivered $41.46 billion (+23.8%) and $25.11 (+31.1%)
Those figures come straight from the Q1, Q2 and Q3 releases filed with the SEC. Against that history, a consensus 0.8% above the revenue guide is less a forecast than an echo of it. CEO Sanjay Mehrotra framed the quarter in June: “Micron’s record fiscal Q3 financial results and even stronger outlook for Q4 reflect the strategic value of memory in the AI era.”
Quick Take: The $50 billion guide includes a 14th week. On a per-week basis it implies about 12% growth, below TrendForce’s 13-18% DRAM contract-price forecast. Micron has beaten its own revenue midpoint by 9-28% in each of the last three quarters.
Industry Response: Suppliers Sold Out, Buyers Warning of Worse
The supply side is not easing into the print. TrendForce’s second-quarter tracker put total DRAM industry revenue at $154.73 billion, up 59.5% quarter on quarter. Samsung led with $60.98 billion and a 39.4% share, SK hynix followed with $38.59 billion and 24.9%, and Micron grew fastest among the three, up 65.5% to $36.0 billion for a 23.3% share, per Evertiq’s report of the TrendForce data. Counterpoint’s tracker, which FinanceFeeds covered in Micron has closed to one point behind SK Hynix in DRAM, put Micron’s share at 25%. The two trackers differ on the level but agree on direction.
Inventories tell the same story. A September 7 KB Securities report found that Samsung and SK hynix held fewer than 10 days of finished memory inventory, against the 30 to 45 days a healthy DRAM market carries, according to Tech Times. Industry sources told Digitimes in August that suppliers had already completed much of their 2027 capacity-allocation talks, Seeking Alpha reported.
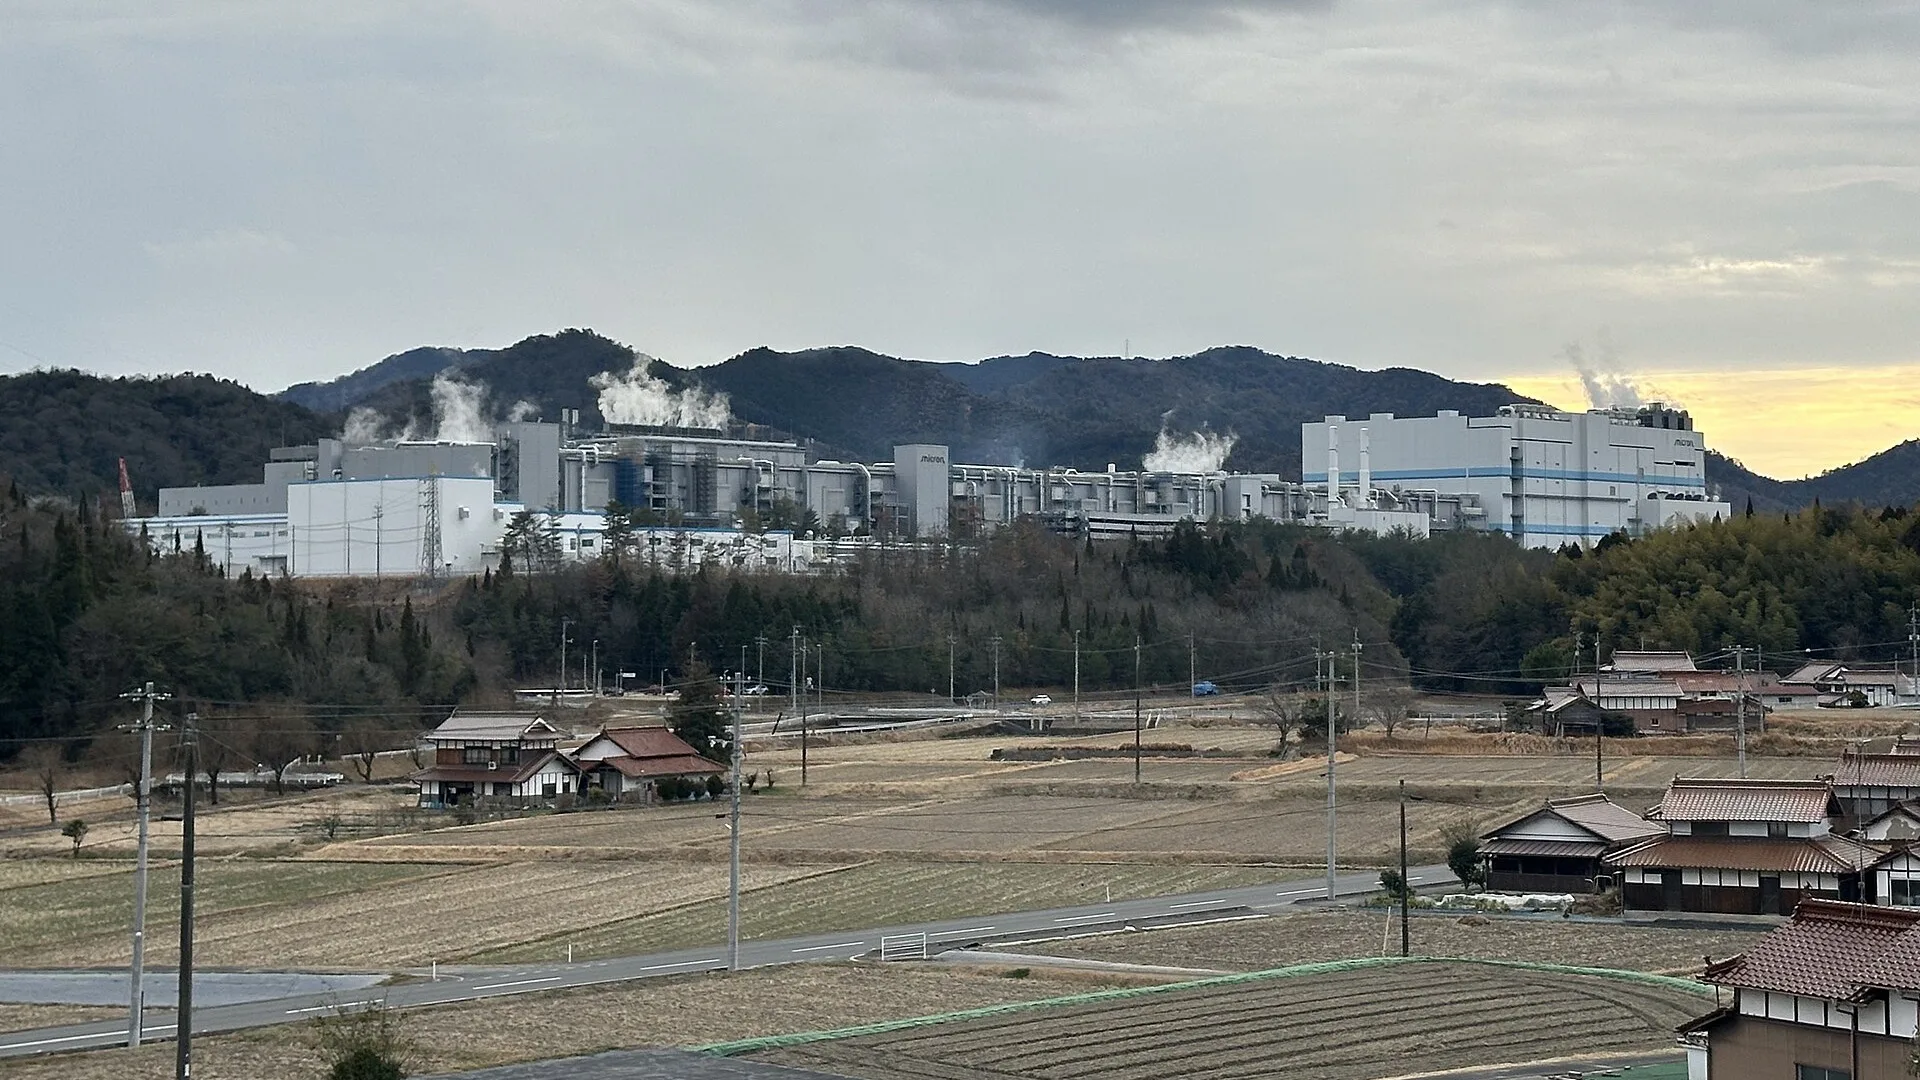
Micron itself is responding in three ways. First, contracts: the 10-Q describes new strategic customer agreements “structured as take-or-pay agreements, with binding commitments for specific volumes over the multi-year contract terms.” Pricing for most is “either fixed, or is subject to minimum and maximum pricing.” Remaining performance obligations tied to those agreements were about $5 billion at the end of May, with $422 million already booked as contract liabilities. Second, product: HBM4 on 1-beta DRAM is “in high-volume shipments for our lead customer’s platform,” with qualification samples at multiple other customers, and HBM4E on 1-gamma is targeted for volume production in calendar 2027. Third, capacity: the 10-Q says Micron is “modernizing our Hiroshima manufacturing facility to support future DRAM nodes and AI memory production” and building an HBM advanced packaging plant in Singapore.
Customers are feeling it. Intel CEO Lip-Bu Tan told the AI Infrastructure Forum in Santa Clara on September 15, per the Seoul Economic Daily: “When I said early last year that memory could become a big bottleneck, I don’t think many people realized it,” Tan said. “It actually happened, and the situation will get worse.” He added that “memory prices have risen five to seven times.” Two days later, Nvidia’s Jensen Huang told reporters in Scotland, per CNBC: “I expect Nvidia to sell twice as many chips as this next year as we do this year.” Every one of those chips needs memory. For the other side of the memory trade, see our SanDisk stock price prediction.
Quick Take: Suppliers are running on under 10 days of inventory and allocating 2027 capacity now. Micron is locking customers into take-or-pay deals with price floors and ceilings, which protects volume but can cap price upside.
Market Impact and Data: What the Print Must Show
Here is the data synthesis the consensus number hides. Sell-side estimates cluster tightly around the guide: TipRanks shows $31.14 and $50.42 billion, while Benzinga cites $31.16 and about $50.4 billion. The Polymarket contract uses a higher reference, $32.22, that it describes as the Street consensus “as of market creation”. It trades at 94% yes. That market is small and thinly traded, so treat it as a sentiment gauge rather than a forecast. Still, traders are betting that Micron clears the top of its own EPS range ($32.00), not just the midpoint.
Apply Micron’s last three beats mechanically and the numbers get large. A repeat of the fiscal Q3 revenue beat (+23.8%) would imply about $61.9 billion. A repeat of the Q3 EPS beat (+31.1%) would imply about $40.64. I don’t expect either. The price environment has changed: last quarter’s DRAM revenue rose on price increases in the low 60s, and the current quarter’s contract increases are forecast in the teens. The more realistic question is whether Micron lands nearer $52 billion to $54 billion, which would still be a 4% to 8% beat against a guide that already includes the extra week.
| What would read as bullish on Sep 30 | What would read as bearish on Sep 30 |
|---|---|
| Revenue well above $51.0bn, i.e. weekly run-rate growth above TrendForce’s 13-18% price range | Revenue at or below the $50.0bn midpoint, meaning weekly growth near 12% or less |
| Gross margin above the ~86% guide (Q3 non-GAAP was 84.9%) | Gross margin flat to Q3, suggesting price gains have stalled |
| Fiscal Q1 2027 guide that grows on a 13-week basis, with the extra week stripped out | A Q1 guide that falls against Q4 once the 14th week drops out, read as a peak |
| HBM4 qualification wins at additional customers named or quantified | Commentary that take-or-pay price bands are capping realised prices |
| Rising strategic-agreement obligations above the ~$5bn disclosed in May | Labour disruption in Taiwan affecting output guidance |
The third row matters most. Because fiscal Q4 carries 14 weeks, fiscal Q1 2027 drops back to 13. A guide for next quarter that is flat or slightly down against $50 billion-plus could still represent healthy weekly growth, and a headline-driven market could misread it.
On valuation, the stock is cheap on simple arithmetic. Annualising the $31.00 EPS guide gives $124, or about 8.2 times the September 18 close of $1,015.80. Normalising to 13 weeks raises that to about 8.8 times. The analyst range on TipRanks runs from Goldman Sachs’ Hold at $1,100 to an average target of $1,563.93, with 29 Buys and one Hold. Mizuho’s Vijay Rakesh trimmed his target to $1,300 from $1,375 and kept a Buy, citing “some multiple compression from concerns around de-specing on future GPU/ASICs.” Our Micron vs Nvidia stock comparison covers why the market is reluctant to pay a higher multiple on those earnings.
Quick Take: Consensus hugs the guide; Polymarket prices a beat above the top of the range. Normalise both Q4 and the Q1 2027 guide to 13 weeks before judging the reaction, or the extra week will distort the read.
Regulatory Landscape and Tension: Tariffs, Subsidies and Labour
The policy risks are not headline risks for September 30, but they shape the guide. The first is trade. Micron’s 10-Q notes that on April 14, 2025, the US Bureau of Industry and Security opened a Section 232 investigation into imports of semiconductors, equipment and derivative products, and warns that it “may result in industry-wide additional tariffs and trade restrictions.” About 80% of Micron’s 2025 revenue came from products shipped to customer locations outside the United States, according to the same filing.
The second is subsidy strings. Micron’s buyback authorisation is “subject to market conditions, restrictions applicable under our CHIPS Act direct funding agreements.” It repurchased no shares in fiscal Q3 and $650 million over the first nine months. For shareholders who expect a cash windfall from 84.9% gross margins, the CHIPS agreements and the US fab build-out compete for that cash. Operating cash flow was $25.39 billion in fiscal Q3, against net capital expenditure of $7.1 billion.
The third is industrial policy abroad. Micron’s Sanand, Gujarat assembly and test plant opened in early March 2026 with a combined investment of about $2.75 billion from Micron and its government partners, and expects to process tens of millions of chips in 2026, scaling to hundreds of millions in 2027, per Computer Weekly. Some social media posts this month presented the plant as a new opening; it is six months old, and the 10-Q describes it as starting to ramp this year. India’s electronics and IT minister Ashwini Vaishnaw said at the inauguration: “India is now moving from being a consumer of chips to becoming a global hub for semiconductor manufacturing and innovation.”
The fourth is labour, which is a legal process, not a regulation, but it runs through Taiwan’s mediation system. Micron’s Taichung and Taoyuan unions are in formal mediation over a demand for a permanent 15% share of global operating profit, as FinanceFeeds reported in Micron’s Taichung union went into mediation. No strike or production interruption has been reported.
What Happens Next: Three Predictions for September 30
Prediction 1: Revenue lands above $51 billion. Weekly run-rate growth of 12% sits below TrendForce’s DRAM contract-price forecast before any contribution from bit growth or HBM4 mix. Micron has cleared the top of its revenue range in each of the last three quarters. The causal chain is simple: prices rose at least in line with the forecast, the 14th week adds volume, and the take-or-pay contracts set floors under pricing. I expect a beat, but in single digits against the midpoint rather than the 24% to 28% of the last two quarters.
Prediction 2: The fiscal Q1 2027 guide is the stock’s real catalyst, and it will be misread at first. Because Q1 returns to 13 weeks, a guide around $50 billion would imply weekly growth of about 8% from the Q4 midpoint. Expect a first-minute reaction to the headline number, then a correction once analysts normalise for the calendar.
Prediction 3: Pricing commentary replaces volume commentary. TrendForce said in July that from the third quarter the main source of server DRAM price increases would shift to customers without long-term agreements and to supply sold outside those agreements. Micron’s strategic agreements are exactly that kind of contract. Listen for how much of fiscal 2027 supply is already committed under price bands. That share determines how much of the Citi-style shortage upside Micron can actually capture. Citi’s September note projects HBM bit demand rising 62% to 75.2 billion gigabits in 2027 and 69% to 127.0 billion gigabits in 2028, with shortages lasting through 2031, per Yahoo Finance.
The September 30 report will not settle the memory cycle. It will show whether Micron is still growing faster than the price of its chips once the calendar is adjusted.
FAQ: Micron Earnings Date and Q4 Expectations
When is the Micron earnings date for fiscal Q4 2026?
Micron reports fiscal fourth-quarter 2026 results on Wednesday, September 30, 2026, with the conference call at 2:30 p.m. Mountain Time, after the US market close. The company announced the date in an August 26 press release. The quarter contains 14 weeks, so the report also closes Micron’s 53-week fiscal year 2026.
What did Micron guide for Q4 2026?
In its June 24 release Micron guided revenue of $50.0 billion plus or minus $1.0 billion, gross margin of about 86%, and non-GAAP diluted EPS of $31.00 plus or minus $1.00. GAAP EPS guidance was $30.73 plus or minus $1.00. Consensus estimates sit close to those midpoints, at about $31.14 in EPS and $50.42 billion in revenue.
Why does the 14-week quarter matter for Micron earnings?
An extra week adds roughly one-thirteenth more selling time than a normal quarter. On a per-week basis the $50 billion guide implies about 12% growth from fiscal Q3, not the 21% the headline suggests. It also means the next quarter, back at 13 weeks, can look weaker on paper even if weekly sales keep rising.
Is Micron expected to beat earnings on September 30?
Micron has beaten the midpoint of its own revenue guide in each of the last three quarters, by 9%, 28% and 24%. A Polymarket contract prices a 94% chance that non-GAAP EPS exceeds $32.22. That market is thinly traded, and a beat of that kind is already expected, so the size of the beat and the next guide will likely drive the share price.
How does HBM4 affect Micron’s fiscal Q4 results?
Micron says HBM4 on its 1-beta DRAM process is in high-volume shipments for a lead customer’s platform, with samples at several other customers. HBM carries higher prices per bit than standard DRAM and consumes more wafer capacity, so a rising HBM mix can lift revenue and margin even when conventional DRAM contract price growth slows.
What are the main risks to Micron stock after earnings?
The main risks are a beat smaller than recent quarters, a next-quarter guide that looks flat because it has one fewer week, price bands in take-or-pay contracts limiting upside, a possible US Section 232 tariff outcome, and the labour mediation in Taiwan. Valuation is about 8 times annualised guided EPS, so expectations are high on growth, not on the multiple.